
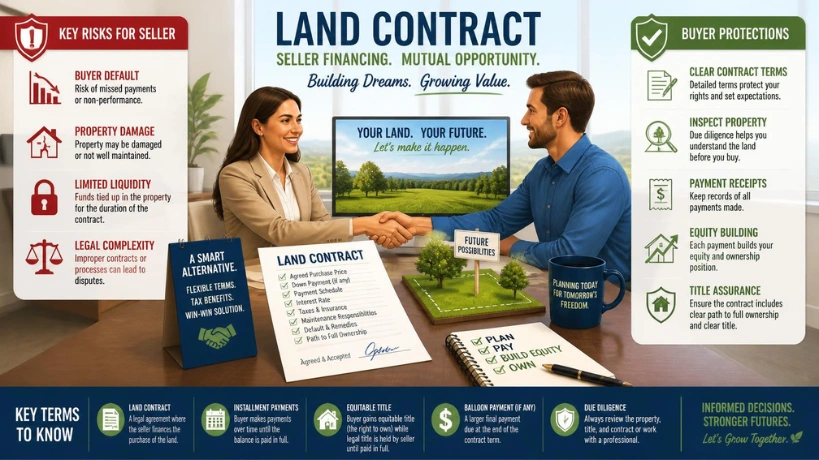
A land contract is a seller-financing arrangement in which the buyer pays the property seller over time instead of using a traditional mortgage lender. The buyer usually takes possession and assumes many ownership costs, while the seller keeps legal title until the agreed balance is paid. For a closer look at this, see What Is A Registered Agent For Llc.
Direct answer: In this type of real estate agreement, the seller finances some or all of the purchase price. The buyer makes a down payment and scheduled installments. Legal title usually remains with the seller until payoff. Because buyer protections differ sharply across U.S. states, careful contract, title, and legal review matters before signing.
| Topic | What to know |
| Financing | The property seller acts as the financing source. |
| Legal title | Usually stays with the seller until the balance is paid |
| Possession | The buyer commonly takes possession during the payment period. |
| Taxes and repairs | The agreement often makes the buyer responsible. |
| Interest | Negotiated between the parties, subject to applicable law |
| Balloon payment | Some agreements require a large final payment. |
| Default | Remedies and buyer protections vary by state. |
| Recording | Requirements differ, but recording can help document the buyer’s interest. |
| Main risk | Buyers can carry ownership costs before receiving the deed. |
| Best precaution | Review the title, financing terms, state law, and the exit plan before signing. |
Key Takeaways
- Seller financing may help a buyer who cannot obtain a conventional mortgage.
- Delayed transfer of the deed creates risks that don’t exist in the same way with a standard mortgage.
- Balloon payments, title problems, unrecorded agreements, and default terms deserve close review.
- State protections differ substantially across the United States.
- Buyers and sellers should use independent legal and tax professionals before committing to a major real estate transaction.
For more property-related explanations, you can also browse Wordspira’s Real Estate guides.
How a Land Contract Works

The basic structure is direct seller financing. Instead of receiving the full purchase price from a bank-funded closing, the seller agrees to receive payments over time.
A typical transaction follows this sequence:
- The buyer and seller agree on the purchase price.
- They negotiate the down payment, interest rate, payment amount, and repayment period.
- The buyer takes possession under the written agreement.
- The buyer makes scheduled payments directly to the seller or through a servicing arrangement.
- The buyer may also pay taxes, insurance, maintenance, and repairs if the agreement assigns those costs.
- After the required balance is satisfied, the seller transfers the deed as required by the agreement and applicable law.
The buyer is commonly described as holding an equitable interest while the seller retains legal title. The exact legal effect of that interest depends on state law.
Land contract: Some deals use a shorter contract term than the payment schedule used to calculate the monthly amount. That structure can leave a large unpaid balance due at the end. This final lump sum is known as a balloon payment. Pew research has identified balloon payments as a significant risk in alternative home financing.
Seller Financing vs. a Traditional Mortgage
The biggest difference is who provides financing and when the buyer receives legal title.
| Issue | Seller-financed agreement | Traditional mortgage |
| Financing source | Property seller | Bank, credit union, or mortgage lender |
| Deed | Usually remains with seller until payoff | The buyer generally receives the deed at closing. |
| Terms | Privately negotiated | Governed by lender program and underwriting |
| Qualification | May be more flexible | Formal income, credit, and underwriting standards |
| Balloon payment | May be included | Much less common in ordinary residential mortgages |
| Default process | Depends heavily on state law and contract | Established mortgage and foreclosure framework |
| Consumer protections | Can vary significantly | More standardized lending protections |
Seller financing can create access where conventional lending is unavailable. It can also shift more risk to the buyer because legal ownership may be delayed for years.
What Buyers Should Check Before Signing
Start with the property title, not the monthly payment. A buyer should confirm that the seller owns the property and identify mortgages, tax liens, judgments, or other claims that could affect ownership.
The CFPB’s research on contracts for deed has documented problems involving title defects, unrecorded buyer interests, property conditions, inflated prices, and costly repairs.
Before signing, buyers should review at least these points:
- Who owns the property now?
- Is there an existing mortgage or other lien?
- Will the agreement be recorded in county land records?
- What are the purchase price, interest rate, and total payment schedule?
- Is there a balloon payment, and when is it due?
- Who pays property taxes and homeowners insurance?
- Who handles repairs and major structural problems?
- Is early payoff allowed without a penalty?
- What events count as default?
- How much time does the buyer have to cure a missed payment?
- What must happen before the deed is transferred?
An independent inspection and professional title search can reveal problems that a private payment agreement doesn’t solve.
The Biggest Risks for Buyers
Delayed legal ownership
The buyer may pay for the home, maintain it, and improve it for years while the deed remains in the seller’s name. That creates a different risk profile from an ordinary mortgage purchase. A dispute over title, liens, recording, or the seller’s ability to convey the property can become expensive.
Balloon-payment risk
A low monthly payment can look affordable while hiding a large balance due later. If refinancing is needed, the buyer must still qualify when the balloon date arrives.
Pew’s 2026 Wisconsin research notes that buyers may need conventional financing later to satisfy such a balance. It also identifies balloon payments as a recurring problem in these transactions.
Property costs before receiving the deed
Buyers commonly assume taxes, insurance, repairs, and maintenance during the agreement. CFPB consumer information describes these costs as typical buyer responsibilities in a contract-for-deed arrangement. The written terms should state exactly who pays each bill and how payment will be verified.
Loss after default
Default may involve more than missing the monthly installment. Failure to pay taxes, maintain insurance, or meet other written obligations can also create problems.
What a seller can do after default depends on state law. Some jurisdictions provide substantial cure or foreclosure rights. Others offer much less protection.
State Law Can Change the Result
There is no single nationwide set of state rules for these transactions. Current 2026 research shows how large the differences can be.
Texas has some of the strongest protections in the country. Pew reports that its rules include contract recording, seller disclosures, annual statements, cure periods, and significant protections against forfeiture.
New Mexico, by contrast, has no state law specifically protecting these buyers, according to Pew’s March 2026 review.
Wisconsin does not require sellers to record these agreements and permits a strict foreclosure process that can move differently from ordinary mortgage foreclosure.
These examples show why a generic online template isn’t enough. The contract needs to fit the law of the state where the property is located.
There is also an important federal update. The CFPB issued a 2024 advisory opinion addressing Truth in Lending Act protections for contracts for deed, but the Bureau withdrew that advisory opinion on May 12, 2025. It is no longer current CFPB guidance. A real estate attorney can determine which current federal and state rules apply to a specific transaction.
What Sellers Should Consider
Seller financing can expand the pool of potential buyers and create an installment income stream. It also turns the seller into a creditor with continuing responsibilities and risks. The agreement should address payment processing, late payments, insurance, property condition, taxes, default procedures, recording, and deed transfer.
Taxes also deserve attention. IRS Publication 537 explains that qualifying property sales with at least one payment received after the tax year of sale may fall under installment-sale rules. A buyer’s future payment obligation can take the form of a note, mortgage, deed of trust, or similar instrument.
The seller should speak with a qualified tax professional about gain recognition, interest income, basis, and reporting requirements.
Long-term seller financing can also become part of broader family and asset planning. Wordspira’s guides to what an estate includes and working with a trust attorney provide useful background on those topics.
When Seller Financing May Make Sense
The arrangement may be worth considering when both parties understand the risks and the property has clean, verifiable title.
For a buyer, a stronger situation usually includes:
- A realistic payment amount.
- No hidden or unaffordable balloon.
- A completed title search and property inspection.
- Clear tax, insurance, and repair duties.
- A recorded agreement when required or advisable under local law.
- A practical plan for final payoff or refinancing.
- Independent legal review.
A weak deal has the opposite features: unclear ownership, undisclosed liens, vague default language, no realistic payoff plan, or pressure to sign without review.
A Safer Three-Part Review: Title, Terms, Exit
Before committing, test the deal in three layers.
Title: Can the seller prove clear ownership and have all liens or existing claims been identified?
Terms: Can you explain the price, interest, monthly payment, taxes, insurance, maintenance, default rules, and final amount without guessing?
Exit: What happens at the end? Know when the deed transfers, whether refinancing will be needed, and what happens if a payment problem arises.
Before You Sign
Don’t judge seller financing only by whether the monthly payment fits your budget. Verify the property, the seller’s title, every payment term, and the legal path to ownership.
Buyers should obtain an independent title review, inspect the property, calculate the full payment obligation, and have a local real estate attorney review the agreement.
Conclusion
A land contract can provide a useful alternative to traditional mortgage financing by allowing a seller to finance some or all of a property’s purchase price while the buyer makes scheduled payments over time. However, the arrangement can also create important risks because the buyer commonly takes possession and assumes costs such as taxes, insurance, maintenance, and repairs while the seller continues to hold legal title until the agreement is satisfied.
The most important step is to look beyond the monthly payment. Buyers should carefully investigate the property’s title, existing liens, payment terms, interest rate, balloon-payment requirements, responsibilities for property expenses, default provisions, recording requirements, and the conditions for transferring the deed.
Frequently Asked Questions
Often, yes. Names vary by state and local practice. You may also see terms such as “installment land agreement,” “land sale contract,” “bond for deed,” or “real estate contract.” The legal treatment still depends on the jurisdiction and the document’s actual terms.
The buyer commonly pays property taxes during the payment period, even though the seller may still hold legal title. The written agreement should clearly assign this responsibility and explain how payments are verified.
Potentially. Buyers sometimes seek a conventional mortgage later to pay the remaining balance, especially when a balloon payment is due. Approval isn’t guaranteed, so a deal shouldn’t depend on future refinancing without a realistic qualification plan.
The answer depends on the contract and state law. A buyer might receive a cure period, face foreclosure, or encounter another remedy permitted by local law. Texas and Wisconsin illustrate how different state procedures can be.
For a significant seller-financed real estate purchase, independent legal review is a sensible safeguard. An attorney licensed in the property’s state can review title, recording requirements, default provisions, disclosures, and deed-transfer terms.

